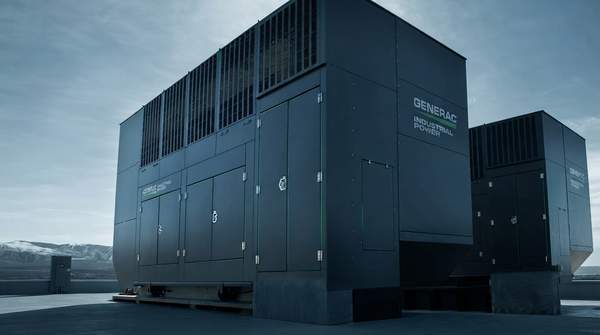
As hyperscale data centers demanding 100 or more megawatts strain electric grids across the United States, a growing number of states are turning to a structural workaround: letting these facilities generate their own power "behind the meter" rather than drawing everything from the regulated grid. In 2025, data center energy legislation passed in Maryland, Ohio, Utah, and West Virginia to address how such facilities can access power without straining the grid, according to tracking by MultiState, a government relations firm. The legislative responses vary widely — from Ohio's framework for "mercantile customer self-power systems" to West Virginia's microgrid districts — but all confront the same underlying tension: how to capture the economic development data centers bring without shifting grid costs onto residential ratepayers or undermining reliability and clean energy commitments.
Understanding Behind-the-Meter Data Centers
The traditional model is straightforward: a data center signs a power purchase agreement with an electric utility and draws grid-supplied electricity, typically requiring transmission-level interconnection to the bulk power system. Behind-the-meter generation inverts that arrangement. As MultiState explains, it allows facilities to self-generate power or contract directly with suppliers instead of relying solely on grid-supplied electricity through traditional utility agreements — in some configurations bypassing the grid entirely.
The distinction matters because of what it changes legally and financially. Hogan Lovells Cadwalader, in an analysis of state initiatives on surging data center power demand, notes that states hold the primary role in regulating the supply and delivery of power to end users in the U.S. Kirkland & Ellis similarly observes that retail power sales made directly from a generator to a data center typically fall under state jurisdiction, not federal FERC oversight. A data center that generates on-site therefore steps largely outside the regulated utility framework — a move that reshapes who pays for the grid, who regulates the generation, and how quickly a facility can be energized.
Speed is a central part of the appeal. Pillsbury Law, analyzing state regulatory approaches to powering data centers, reports that projects avoiding transmission-level interconnection can reduce time to power to roughly three to six years, making "bring your own generation" a prevalent hyperscale strategy. The trade-off, the firm cautions, is that such unplugged systems may present stranded asset risk and greater financing challenges — a facility locked into on-site generation carries costs that persist even if demand or technology shifts.
Why Data Centers Seek Behind-the-Meter Solutions
The driver is scale. The sheer power demanded by large data centers has motivated lawmakers to explore alternatives to conventional utility service, as MultiState's reporting puts it. Where a single hyperscale campus can require as much power as a small city, the queue for transmission interconnection and the pace of utility infrastructure buildout become binding constraints on business plans. On-site generation or direct contracts with suppliers offer a path around those bottlenecks.
Reliability and energy independence also factor in. The National Caucus of Environmental Legislators, surveying the landscape, notes that the rapid development and significant power demand of data centers present unique challenges for grid reliability, affordability, and decarbonization — pressures that push operators toward solutions that insulate them from grid constraints. Behind-the-meter arrangements can also insulate operators from tariff structures designed to recover grid costs, which is precisely what worries ratepayer advocates.
That concern is not abstract. Clean Energy Group reports that as Americans wait on finalized federal legislation and interconnection rules, a growing number of states have taken action to protect ratepayers from increased energy bills attributed to data centers. The fear among advocates is that when a large customer self-generates or exits the utility system, the fixed costs of the shared grid — transmission, distribution, and generation built to serve expected load — do not disappear; they get spread across the remaining customers. The World Resources Institute captures the broader community anxiety: a surge of new data centers is reshaping local energy grids, water systems and land use, often with limited public information about long-term impacts, and rising power bills tend to be top of mind.
Behind-the-Meter Data Centers: An Explanatory Model
The framework below deconstructs the concept into its operational model, the stakeholders with a direct stake in the outcome, and the policy goals state legislation is trying to reconcile. The traditional grid-supply row is included as the baseline against which behind-the-meter arrangements are defined.
| Component | How it works | What is at stake |
|---|---|---|
| Traditional grid supply | Data centers rely on the existing electric grid, typically requiring transmission-level interconnection and power purchase agreements with utilities. | Baseline model; interconnection queues and grid capacity constrain how quickly facilities can be powered. |
| Behind-the-meter generation | Data centers generate electricity on-site or contract directly with suppliers, reducing or eliminating reliance on the grid and avoiding transmission-level interconnection. | Can cut time to power to roughly three to six years, per Pillsbury Law, but carries stranded asset risk and financing challenges. |
| Data center operators | Seek reliable, cost-effective power and faster deployment — interests inferred from the benefits behind-the-meter arrangements offer. | Speed to power and cost certainty; freedom from some utility regulation. |
| Electric utilities | Responsible for grid stability amid unprecedented load growth. | Must adapt to accommodate data centers while maintaining reliability for all customers. |
| Ratepayers | Concerned about rising bills and the risk that data centers shift grid maintenance costs onto them. | This concern is a driving factor for state legislative action, per Clean Energy Group. |
| Policymakers and regulators | Navigate competing objectives: economic development, grid stability, ratepayer protection, and environmental goals. | States hold primary authority over retail electricity sales and generation resource mix, per Kirkland & Ellis. |
Read together, the rows show why behind-the-meter policy is not a single decision but a chain of them: an operational choice by the operator becomes a revenue question for the utility, a cost question for ratepayers, and a jurisdictional question for regulators — all before any environmental accounting begins.
State Legislative Approaches to Behind-the-Meter Data Centers
Ohio offers the most developed example. House Bill 15 and the related Senate Bill 2 create pathways for large energy users to source power outside the regulated utility framework, with approaches that vary in balancing utility contracts against competitive market access, as MultiState reports. The legislation encourages "mercantile customer self-power systems" — arrangements in which large customers generate their own power and, if they do not utilize the distribution system, can operate without certain utility regulations.
Legal analyses of the bill by Bricker Graydon and Calfee highlight its companion ratepayer provisions: electric distribution utilities face new rate case deadlines, and the Public Utilities Commission of Ohio gains authority intended to align rates with grid costs. Kirkland & Ellis notes that retail power sales made directly from a generator to a data center fall under state jurisdiction — the legal foundation on which such self-supply arrangements rest.
Other states have taken different routes to the same end. Utah's SB 132 similarly creates pathways for large energy users to source power outside the regulated utility framework. West Virginia's HB 2014 takes a microgrid approach, enabling facilities to operate in certified districts independently from residential ratepayer grids while supporting clusters of data centers in the same area. Maryland also enacted data center energy legislation in 2025. Maryland, Utah, and West Virginia are noted for encouraging behind-the-meter generation generally, though the specific mechanisms differ.
The broader legislative current runs in several directions at once. The National Caucus of Environmental Legislators counted 65 pieces of legislation introduced across 22 states in 2025, with most bills focusing on ratepayer protections, energy use transparency, renewable requirements, and siting processes. MultiState's 2026 tracking observes that as the scale of energy demand becomes clearer, states are considering measures ranging from consumer and environmental protections to outright moratoriums on new data centers — with the caveat that early-session bills may be amended or substituted during the legislative process.
Navigating Policy Trade-offs: Grid, Economy, and Environment
The core difficulty is that every adjustment redistributes risks and benefits among data center developers, utilities, and public ratepayers, as Rachel Mural, Dipesh Pherwani, and Chaitanya Gupta of the Belfer Center write in their comparison of the Virginia and Texas experiences. Policymakers must support the digital economy, they argue, without unraveling public protections on electricity costs and environmental damages — and despite growing federal interest, the majority of data center energy legislation continues to occur at the state level.
Pillsbury Law frames the same balancing act from the regulator's chair: legislatures, public utility commissions, governors' offices, utility executives, and ratepayer advocates are all responding to unprecedented load growth, grid reliability concerns, and water and land use impacts — while weighing those pressures against the significant economic growth and tax base expansion data centers provide. Hogan Lovells Cadwalader adds that states must juggle grid reliability, ratepayer protection, and clean energy commitments simultaneously, and cautions that it is still too early to opine on the effectiveness of these initiatives, including their impacts on local grid reliability and retail rates.
Environmental alignment is the least settled dimension. Behind-the-meter systems are subject to state energy regulatory jurisdiction rather than federal oversight, which means clean energy commitments play out differently depending on the fuel a facility chooses and the state's generation resource mix rules. The World Resources Institute's community-level reporting — rising power bills, water use, and land use pressures — underscores that these are not merely technical questions but ones with visible local consequences.
Policy Implications and Future Monitoring
Policymakers should develop legislative frameworks that enable behind-the-meter data center growth while explicitly addressing grid stability, fair cost allocation for ratepayers, and alignment with broader energy goals. The state record so far suggests the workable models pair an enabling mechanism — self-power systems, microgrid districts, direct-supply pathways — with an explicit answer to who pays for the grid those facilities may still occasionally rely on. Ohio's combination of self-power authorization with rate case reform and PUCO cost-alignment authority illustrates the pattern; states that enable self-generation without that second half leave the ratepayer question open.
The measurable indicator to watch is the passage of new state legislation or regulatory rulings that either encourage or restrict behind-the-meter data center development, specifically detailing cost allocation mechanisms or grid interconnection requirements. With dozens of bills moving across more than 20 states and early-session language subject to amendment, the specifics of those cost-allocation provisions — not the headline question of whether states permit self-generation — will determine whether behind-the-meter power becomes a genuine balance of economic development and ratepayer protection or a transfer of grid costs onto households.
Sources
- States Look at Ways to Encourage Off-the-Grid Power for Data Centers — Multistate
- State legislative and regulatory initiatives to address concerns caused by the surging… — HLC
- Your Questions Answered: What Data Centers and Energy-Intensive Infrastructure Developers and Operators Need to Know — Klgates
- State Energy Regulatory Approaches to Powering Data Centers — Pillsbury Law
- States Act to Align Data Center Energy Demand with Climate Goals — National Caucus of Environmental Legislators
- States are stepping up to protect households from rising energy bills due… — Clean Energy Group
- From Energy Use to Air Quality, the Many Ways Data Centers Affect US Communities — World Resources Institute
- Ohio Senate Unveils Energy Legislation: Key Differences Between S.B. 2 and H.B. 15 — Bricker
- State Data Center Legislation in 2026 Tackles Energy and Tax Issues — Multistate
- Data Centers and Large-Scale Electric Growth: The Virginia and Texas Experiences — The Belfer Center for Science and International Affairs