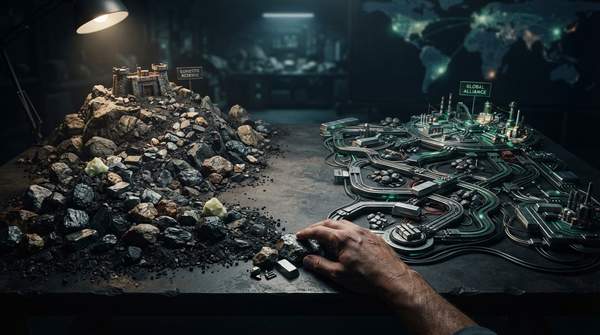
Tokenizing a real-world asset is not one step. It is three. A building, a loan portfolio, or a bond cannot simply be "put on chain" — it must first be legally owned and managed off chain, then connected to a blockchain through a data bridge, and only then represented as a programmable token governed by smart contracts. That is the architecture I want to walk you through, because understanding where each function lives tells you where these projects can fail.
Understanding Real-World Asset (RWA) Tokenization
RWA tokenization means representing off-chain financial instruments — private credit, receivables, loans, fixed-income securities — as programmable digital tokens on public or permissioned blockchains. Jung-Hua Liu's technical analysis of RWA protocols describes it as one of the most consequential innovations at the intersection of decentralized finance (DeFi) and traditional financial markets.
The appeal is straightforward. As Fenwick's securities lawyers note, tokenized RWAs let legal ownership or rights to traditionally illiquid assets be digitized and traded on digital platforms, with expedited settlement and potentially reduced operating costs. Global demand is growing in both the DeFi community and traditional finance.
But the same lawyers flag the catch: regulatory hurdles have slowed adoption in U.S. markets, where issuers must navigate existing securities laws and often lengthy SEC review processes. The mechanics are the easy part. The legal and institutional plumbing is where things get hard.
The RWA Tokenization Stack: A Layered Explanatory Model
Here is the mental model I use. Every RWA project, regardless of asset class, has to solve the same three problems in sequence: establish real ownership off chain, move trustworthy data on chain, and automate the token's lifecycle on chain. Strip away the marketing and you can map any project onto these layers — and, more usefully, onto the failure points between them.
| Layer | What it does | Key components | Where it can fail |
|---|---|---|---|
| Off-chain infrastructure | Establishes legal ownership, custody, and compliance for the underlying asset | Asset lifecycle management, custodians, SPV governance, local compliance | Legal recognition of token ownership; weak property management; no independent party able to act for token holders |
| Integration & data layer | Bridges off-chain asset information to the blockchain for verification and updates | Oracles, data aggregators, risk-assessment providers | Accuracy and security of oracle data feeds feeding the token's on-chain state |
| On-chain layer | Defines token standards, automates processes, and connects to DeFi protocols | Smart contracts, token standards, liquidity venues, settlement rails | Legal enforceability of code; interoperability across ledgers |
The flow runs from top to bottom: value originates in the real asset, data about that value crosses the bridge, and the token on chain represents a claim that is only as good as the two layers beneath it. Liu's analysis frames these as interconnected domains — smart contract layer, off-chain backend, integration layer, regulatory dimension, and organizational engineering — but the three-tier compression captures what a reader evaluating a project actually needs.
Layer 1: Off-Chain Infrastructure and Asset Management
The foundational layer of any RWA architecture, as a systematization of RWA concepts published on arXiv puts it, is the "jurisdictional anchor that binds the on-chain token to the off-chain asset." Before a token means anything, someone must legally own the asset, custody it, and manage it under local law.
This is where tokenization projects have actually broken. A legal guide from Buzko Legal recounts a real estate tokenization failure in which what collapsed was not the smart contracts but the off-chain layer: property management, local compliance, the governance of the special purpose vehicles, and the absence of an independent party able to act for token holders. Once a court restricted rent collection, distributions stopped — and token holders found their claims ran against a web of LLCs and a sponsor in liquidation, not against the houses.
I dwell on this because it inverts the usual narrative. The blockchain did not fail. The legal wrapper did. Any analysis of an RWA project should therefore start off chain: who owns the asset, under what entity structure, and who can enforce token holders' rights if the sponsor disappears?
Layer 2: The Integration and Data Bridge (Oracles)
Once the asset exists and is managed, the blockchain needs to know things about it: its value, its performance, whether a payment was made. Blockchains cannot see the outside world on their own. That is the oracle layer's job.
Tokeny's ecosystem map of the RWA space describes this data layer as a centralized hub for organized data related to tokenized assets, and names the players: Chainlink, whose Web3 services connect smart contracts to real-world data sources and off-chain computation across any blockchain; Moody's for risk assessment; Morningstar for investment insights; and Inveniam, which aggregates data across private assets.
The qualification matters as much as the function. The integrity of the tokenized asset depends on the accuracy and security of these data feeds. A token that reports flawless on-chain performance while its oracle is ingesting stale or manipulated off-chain data is not transparent — it is confidently wrong. When you evaluate an RWA project, ask who supplies the data, how it is verified, and what happens when the feed disagrees with reality.
Layer 3: On-Chain Smart Contracts and DeFi Protocols
The top layer is what most people picture when they hear "tokenization." Smart contracts — self-executing contracts with terms written into code — automate processes such as dividend distributions, governance, and ownership transfers, reducing the need for intermediaries, as Securitize's tokenization guide explains. Issuers must also choose between public and permissioned blockchains, a decision with real compliance consequences.
On this layer sit the token standards and the DeFi connections. Tokeny's ecosystem map highlights the ERC-3643 token standard alongside blockchain networks like Kaia and Polygon, and describes how protocols use consensus mechanisms, cryptographic techniques, and smart contracts to keep data integrity, transparency, and immutability across a network of nodes.
Liu's analysis adds the risk machinery that lives here: capital deployment and redemption logic, yield distribution mechanisms, liquidation triggers, and circuit breakers. The point of this layer is automation — but automation is only as defensible as the legal layer beneath it. Code can execute a transfer instantly; whether a court recognizes that transfer is a Layer 1 question.
Benefits of RWA Tokenization: Liquidity, Transparency, and Accessibility
Why build this stack at all? The World Economic Forum's explainer on asset tokenization gives the core case: tokens are programmable, traceable, and transferable peer-to-peer, each acting as a digital certificate of ownership or a claim to a portion of an asset. Instead of buying an entire commercial building, investors can buy fractions represented as tokens, traded on blockchain-based systems, potentially around the clock and globally.
The efficiency argument is the one Fenwick highlights — expedited settlement and reduced operating costs from digitized ownership rights. Britannica's overview frames the pros as increased accessibility, liquidity, and efficiency.
The transparency argument is the most interesting to me. The arXiv systematization argues that unlike opaque asset-backed security tranches, RWA tranches offer real-time, on-chain verification of underlying loan performance — a "Glass-Box Securitization" model in which credit risk is auditable by any participant in real time. The caveat is structural: that transparency is only as good as the off-chain data pushed through the oracle layer. A glass box fed by an opaque pipeline is still a black box at the source.
Challenges and Considerations: Regulatory Hurdles and Interoperability
The challenges mirror the architecture. At the legal layer, Fenwick describes the path to SEC registration as daunting, with issuers navigating existing securities laws and lengthy review processes. The World Economic Forum lists the brakes on adoption directly: limited interoperability between blockchain networks and legacy infrastructure, unclear legal frameworks for tokenized assets, and liquidity concerns in secondary markets.
There is also a live technical-policy debate about what "tokenization" should even mean. A letter submitted to the SEC in March 2026 by the Prasaga Foundation distinguishes "canonicalization" — a complete digital twin of an object with all lineages, rules, policy, and compliance encapsulated in a self-contained object in the owner's own account, delivering an immutable record of provenance and auditability on chain — from the smart contract model, in which an asset is merely a balance inside a shared contract account, with ownership and transfer logic written independently by each issuer. The letter argues the Commission can examine and enforce against the canonicalized object directly because the ledger natively understands what it is.
That distinction is not academic. It determines whether the on-chain representation carries the asset's full legal and compliance context, or whether that context lives in application-layer code that varies issuer by issuer.
Navigating the Future of Tokenized Real-World Assets
Stakeholders should prioritize the development of robust legal frameworks and interoperable technical standards to unlock the full potential of RWA tokenization. The three-layer model makes the reason plain: the on-chain layer is maturing fastest, but the off-chain legal layer is where projects have actually failed, and the integration layer determines whether on-chain transparency reflects off-chain truth.
The measurable indicators to watch are increased adoption of standardized legal agreements for token ownership and the emergence of widely accepted cross-chain interoperability protocols. When those two things appear together — court-tested ownership wrappers and interoperable token standards — the stack stops being an experiment and starts being infrastructure. Until then, evaluate every RWA project from the bottom of the stack up, not the top down.
Sources
- MEDIUM
- Tokenized Real-World Assets: Pathways to SEC Registration — Fenwick
- SoK of RWA Tokenization: A Systematization of Concepts, Architectures, and Legal Interoperability — ARXIV
- Legal Guide to Real-World Assets (RWA) Tokenization – Buzko Legal
- Real World Asset (RWA) Tokenization Ecosystem Map — TOKENY
- The Tokenization of Real-World Assets (RWAs) — Securitize
- How will asset tokenization transform the future of finance? — World Economic Forum
- Britannica
- SEC